Rental Property Mortgage Payments: Why Principal, Interest, and Escrow Must Be Split
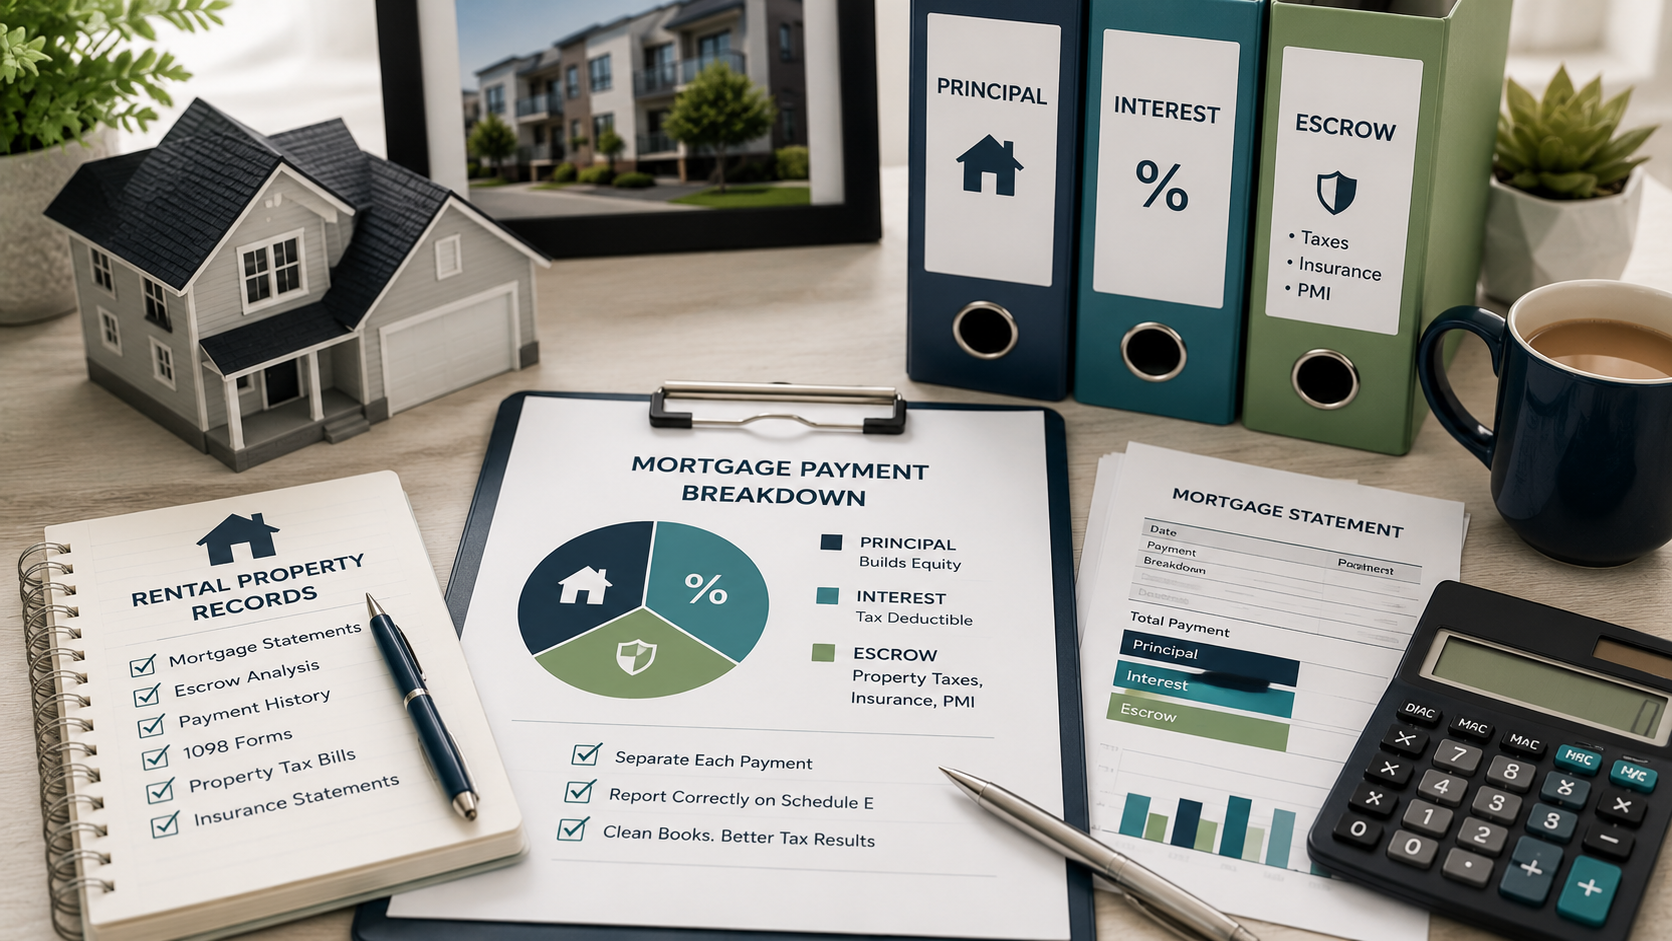
A rental mortgage payment is not one simple tax expense. For clean bookkeeping and tax preparation, landlords usually need to separate loan principal, mortgage interest, escrow deposits, property taxes, insurance, and other mortgage-related items.
Many rental property owners record the full mortgage payment as one expense in their books. That may seem simple, but it can create problems when it is time to prepare the rental tax return. A single mortgage payment may include principal, interest, escrow for property taxes, escrow for insurance, mortgage insurance, late fees, shortage payments, or other loan-related charges.
These items do not all receive the same tax treatment. Mortgage interest may be a rental expense. Property taxes and insurance may also be rental expenses when properly supported. Principal payments, however, reduce the loan balance and should not be treated like an ordinary rental expense on the profit and loss statement.
This article explains why rental property mortgage payments should be split, what records landlords should save, and when a Rental Property Bookkeeping Cleanup project may help before tax preparation.
Quick Guide
Why Rental Mortgage Payments Must Be Split
A mortgage payment is usually made as one monthly payment, but the tax return does not treat every part of that payment the same way. The accounting needs to show what portion went to loan principal, what portion went to mortgage interest, and what portion went into or came out of escrow.
If the full mortgage payment is deducted as a rental expense, the profit and loss statement may overstate expenses. If only the Form 1098 interest is entered but escrow payments are ignored, property taxes or insurance may be missed. If escrow deposits are treated as expenses before the underlying tax or insurance bill is paid, the records may not match the actual tax documents.
Clean mortgage bookkeeping can also help rental property owners understand true cash flow. Principal payments reduce debt, interest is a financing cost, and escrow may be timing-related. When everything is grouped together, it becomes harder to see whether the rental is actually profitable.
The Main Parts of a Rental Mortgage Payment
Most rental mortgage payments contain several parts. The exact split depends on your lender, loan type, escrow setup, and property facts.
| Mortgage Component | What It Means | Why It Needs Separate Tracking |
|---|---|---|
| Principal | The portion of the payment that reduces the loan balance. | Principal is not an ordinary rental expense on the profit and loss statement. It should generally reduce the mortgage liability. |
| Mortgage Interest | The financing cost paid to the lender for the rental property loan. | Mortgage interest may be reported as a rental expense when properly supported and connected to rental use. |
| Escrow Deposits | Amounts collected by the lender to later pay property taxes, insurance, or other escrowed items. | Escrow deposits are not always the same as actual taxes or insurance paid. The year-end escrow statement may be needed. |
| Property Taxes | Real estate taxes paid for the rental property, often through escrow. | Property taxes may be deductible as a rental expense, but they should be supported by the tax bill or escrow disbursement record. |
| Insurance | Rental property insurance, hazard insurance, or landlord policy premiums. | Insurance should be separated from taxes, interest, and principal. Multi-year premiums may need special review. |
| Mortgage Insurance or Fees | Additional lender-related charges that may appear on the mortgage statement. | These items may need separate tax review instead of being grouped into mortgage interest automatically. |
| Escrow Shortage or Surplus | Adjustments caused by changes in taxes, insurance, or escrow estimates. | Shortages and refunds can create confusion if they are treated as regular deductible expenses or income without review. |
How Incorrect Mortgage Bookkeeping Can Delay Tax Preparation
Mortgage bookkeeping issues can slow down tax preparation because the preparer may need to reconstruct the correct split from monthly statements, year-end loan activity, Form 1098, escrow reports, bank records, and property tax bills.
Full Payment Booked as Interest
This can overstate deductible interest and ignore the principal reduction that should be tracked against the loan balance.
Escrow Treated as One Expense
Escrow may include both property taxes and insurance. It may also include timing differences, shortages, or refunds that need review.
Principal Posted to Repairs or Miscellaneous
Principal payments should not be mixed with operating expenses such as repairs, supplies, utilities, or maintenance.
Missing Form 1098 or Escrow Statement
Without the lender’s annual statement, it can be harder to confirm mortgage interest and escrow disbursements.
Want a Cleaner Rental Tax Prep File?
Download the free Rental Property Tax Savings Checklist to help organize mortgage records, escrow statements, rental income, expenses, repairs, improvements, and depreciation records before filing.
Mortgage Records Landlords Should Save
To split mortgage payments correctly, landlords should save more than bank statements. A bank statement may show the total payment, but it usually does not show how the lender applied the payment.
Mortgage and escrow records to gather
- Year-end Form 1098 or mortgage interest statement.
- Annual escrow analysis statement.
- Monthly mortgage statements showing principal, interest, and escrow activity.
- Loan activity report or amortization schedule, if available.
- Property tax bills and proof of payment.
- Insurance declarations page and premium invoices.
- Escrow disbursement records showing taxes and insurance paid by the lender.
- Refinance closing statement, if the loan changed during the year.
- Records for escrow shortage payments, escrow refunds, or lender adjustments.
- Notes showing whether the property was rented, vacant, converted, or partly personal use during the year.
If you own more than one rental property, keep mortgage records separated by property. This helps avoid posting one property’s mortgage interest, taxes, or insurance to another property’s Schedule E activity.
Special Issues When Rental Property Is Also Used Personally
If a property is used partly as a rental and partly for personal use, mortgage interest, property taxes, insurance, and other expenses may need to be allocated between rental and personal use. This can happen with vacation homes, converted homes, duplexes, partial rentals, or mixed-use properties.
In these cases, the mortgage payment split is only the first step. After separating principal, interest, taxes, and insurance, the rental portion may still need to be determined based on the property’s use.
If you use the property personally or rent only part of the property, provide your tax preparer with rental days, personal use days, square footage details, and any records showing when the property was available for rent.
Red Flags Your Mortgage Bookkeeping Needs Cleanup
These red flags may indicate that the rental books should be reviewed before tax preparation.
- The full mortgage payment is booked as mortgage interest.
- The full mortgage payment is booked as one generic rental expense.
- Loan principal is mixed with repairs, supplies, or miscellaneous expenses.
- Escrow deposits are treated as property taxes without reviewing actual tax payments.
- Insurance is included in escrow but not separated in the books.
- Form 1098 does not match the interest expense shown in the bookkeeping records.
- Property tax bills are missing or do not match escrow disbursements.
- Escrow shortages, refunds, or adjustments are posted to the wrong category.
- Multiple rental properties share one mortgage account with no property-level tracking.
- A refinance occurred, but the closing statement and new loan details were not reviewed.
What About Refinancing a Rental Property?
Refinancing can create additional bookkeeping questions because the old loan may be paid off, a new loan may be created, closing costs may be added, escrow may be refunded or re-established, and cash-out proceeds may need to be reviewed.
If you refinanced a rental property, save the closing disclosure, payoff statement, new loan agreement, escrow refund details, and records showing how any cash-out funds were used. Do not assume every refinance-related cost is currently deductible.
Refinancing may also affect interest tracing, basis records, and depreciation questions. If you are unsure how the refinance was recorded, a bookkeeping cleanup or depreciation review may help before filing.
How Small Business Accounting Inc. Can Help
Small Business Accounting Inc. helps landlords, real estate investors, short-term rental owners, and property owners organize rental mortgage records before tax preparation. We can help review bookkeeping categories, reconcile mortgage statements, separate principal from interest, identify escrow activity, and prepare cleaner records for tax filing.
Rental Bookkeeping Cleanup
We help clean up rental books, fix miscategorized mortgage payments, organize escrow activity, and prepare tax-ready records.
Rental Tax Preparation
We help prepare rental tax returns using organized income, expense, mortgage interest, property tax, insurance, and depreciation records.
Depreciation Tax Savings Review
We review depreciation schedules, improvements, property basis, and tax planning questions that may connect to rental property records.
Real Estate Tax & Accounting
We support landlords and investors with broader real estate tax, bookkeeping, and planning questions.
If your mortgage payments were not split correctly, start with our Rental Property Bookkeeping Cleanup service. If your concern is depreciation, basis, improvements, or tax savings opportunities, review our Real Estate Depreciation Tax Savings Review.
Where This Fits in Your Rental Tax System
Mortgage payment cleanup is only one part of rental property tax preparation. Landlords should also organize rental income, repairs, improvements, depreciation schedules, closing statements, property manager reports, short-term rental platform reports, and year-end bookkeeping.
For broader support, visit our Real Estate Tax & Accounting hub page. If you need full tax preparation support, visit our Rental Property Tax Preparation page.
Need Help Splitting Rental Mortgage Payments Correctly?
If your rental books show the full mortgage payment as one expense, Small Business Accounting Inc. can help review the records, clean up the bookkeeping, and prepare a more tax-ready file.
Frequently Asked Questions
Can I deduct the full mortgage payment on a rental property?
Usually, no. A mortgage payment often includes principal, interest, and escrow. Mortgage interest may be a rental expense when properly supported, but principal generally reduces the loan balance and should not be treated as an ordinary rental expense.
How should mortgage principal be recorded for a rental property?
Principal should generally reduce the mortgage loan liability in the books. It should not be mixed with repairs, maintenance, supplies, utilities, or other operating expenses.
What records show rental mortgage interest?
Form 1098, annual mortgage statements, and lender activity reports can help support mortgage interest. Monthly statements may also show the split between principal, interest, and escrow.
How should escrow be handled for rental property bookkeeping?
Escrow should be reviewed carefully because deposits into escrow are not always the same as property taxes or insurance actually paid. Landlords should save escrow analysis statements, property tax bills, insurance invoices, and lender disbursement details.
What if my bookkeeping shows the full mortgage payment as interest?
The books may need cleanup before tax preparation. A review can help separate principal, interest, escrow, taxes, insurance, shortage payments, and other lender charges.
Can Small Business Accounting Inc. help with rental mortgage bookkeeping cleanup?
Yes. Small Business Accounting Inc. provides remote tax and accounting support nationwide for landlords, rental property owners, short-term rental owners, and real estate investors who need help organizing rental books before filing.